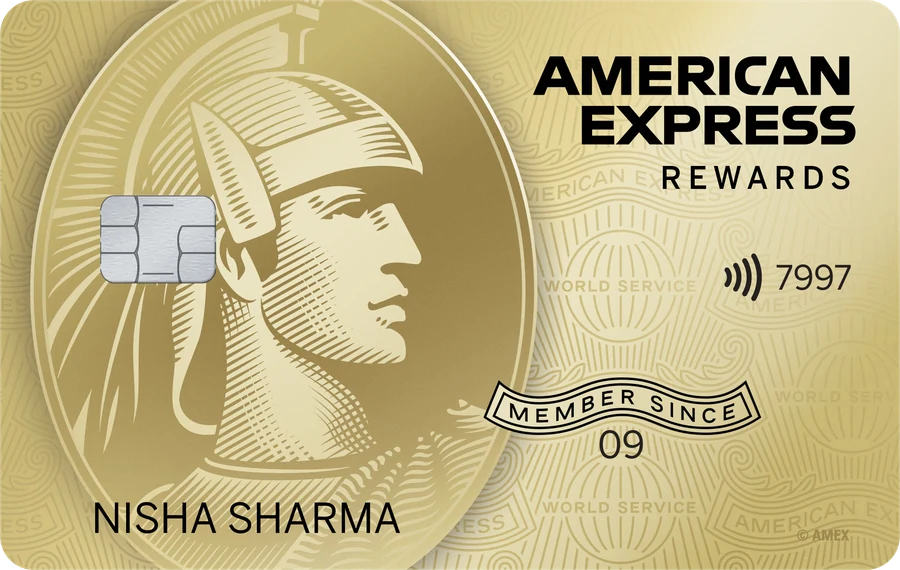
Key facts
- Applications
- Paused for new customers in India
- Joining fee
- ₹1,000
- Annual fee
- ₹4,500 from the second year
- Fee waiver
- Renewal fee waived if you spent ₹1.5 lakh in the previous card year. The 50% waiver for ₹90,000–₹1,49,999 ends on 15 Nov 2026.
- Welcome benefit
- 4,000 MR points after paying the joining fee and spending ₹15,000 within 90 days. 5,000 MR points when you pay the first renewal fee.
- Rewards
- 1 Membership Rewards point per ₹50. No points on fuel, insurance, utilities, cash or EMI at the merchant's checkout or terminal.
- Monthly bonus
- 1,000 points for 4 transactions of ₹1,500 or more in a calendar month, plus 1,000 points for spending ₹20,000 in a month (enrolment required)
- Lounge access
- None
- Forex markup
- 3.5% + GST
- Eligibility
- 18+, income ₹4.5 lakh (salaried) or ₹6 lakh (self-employed), in cities Amex serves
Checked against Amex MRCC page, Amex schedule of fees, Amex customer updates on 28 Oct 2026. Fees exclude 18% GST.
Good
- Monthly bonuses lift a 1-point-per-₹50 base rate
- Low first-year fee
- Membership Rewards points have flexible redemptions
Watch out
- New applications paused in India
- 50% fee waiver ends 15 Nov 2026
- No lounge access
- Amex acceptance is narrower than Visa or Mastercard
Can you get it today?
American Express says it is "temporarily pausing the acceptance of new card applications in India". This applies to this card as of 28 Oct 2026. Existing cardholders aren't affected. If Amex reopens applications we'll update this page and post it on X.
From 15 Nov 2026 Amex is also changing how points work for existing members: points stay with each card instead of being pooled, monthly bonuses are counted by posting date, and you can't earn or redeem points while a payment is overdue.
How it earns
The base rate is 1 point per ₹50. Most of the value is in the two monthly bonuses: 1,000 points for four transactions of at least ₹1,500 in a calendar month, and another 1,000 for ₹20,000 of spend in a month once you enrol. Fuel, insurance, utilities and merchant EMI don't earn.
Who it suits
Someone who can split regular spending into four ₹1,500 transactions each month and who already has a Visa or Mastercard for places that don't take Amex. If you can't hit the monthly pattern, the earn rate is ordinary.